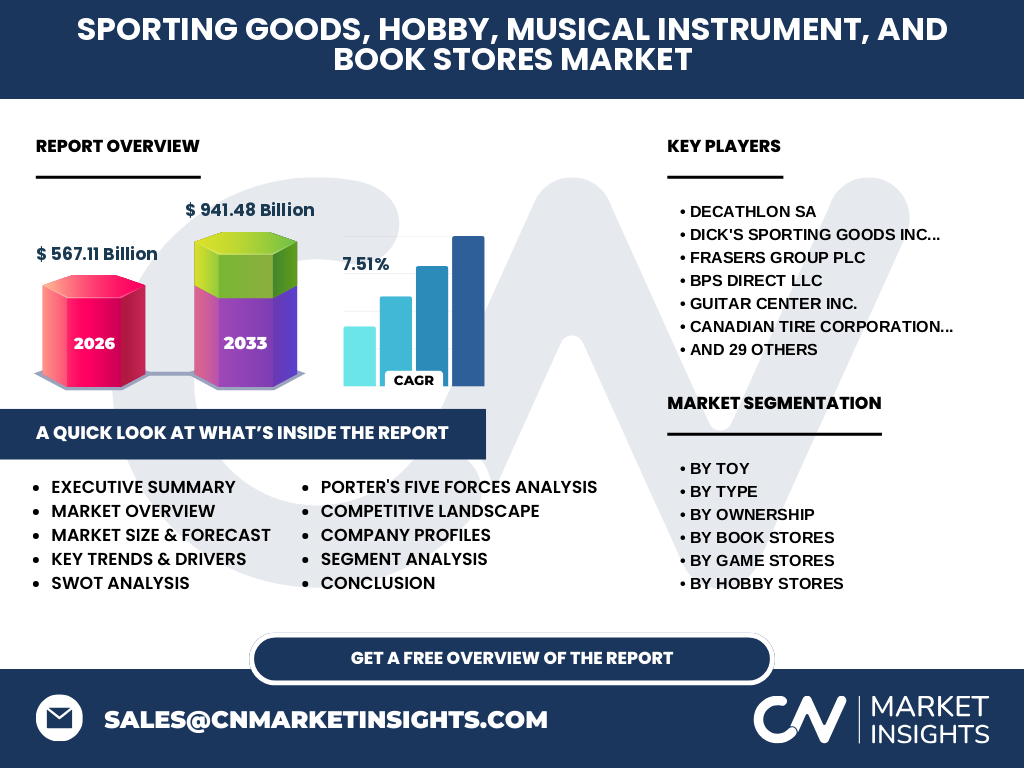
What is the market overview of the Sporting Goods, Hobby, Musical Instrument, and Book Stores Market?
Our analysis indicates that the Sporting Goods, Hobby, Musical Instrument, and Book Stores Market encompasses specialized retail ecosystems covering physical goods like acoustic guitars, fitness equipment, and rare books. Valued at $567.11 Billion in 2026, this sector represents a critical nexus of consumer discretionary spending, balancing brick-and-mortar experiential spaces with surging digital commerce fulfillment networks.
Key market drivers, restraints, challenges, and opportunities shaping Sporting Goods, Hobby, Musical Instrument, and Book Stores Market
Structural drivers include rising participation in outdoor recreation and crafting hobbies. However, supply chain volatility involving raw materials like tonewoods for musical instruments poses severe constraints. Opportunities lie in omnichannel integration for independent retailers to compete against major giants like Decathlon SA and Dick's Sporting Goods Inc.
Emerging trends and growth patterns in Sporting Goods, Hobby, Musical Instrument, and Book Stores Market
The shift toward experiential retail is transforming the Sporting Goods, Hobby, Musical Instrument, and Book Stores Market industry trends. Consumers increasingly demand in-store testing zones for gear from brands like Sweetwater Sound Inc. and Guitar Center Inc., driving higher average ticket sizes and fostering intense brand loyalty across niche enthusiast communities.
How did COVID-19 impact the Sporting Goods, Hobby, Musical Instrument, and Book Stores Market?
Lockdowns catalyzed a massive surge in home-bound hobbies, board games, and fitness equipment purchases. While inventory bottlenecks challenged suppliers, companies like Recreational Equipment Inc. capitalized on outdoor recreation booms. The post-pandemic recovery trajectory stabilized demand, pivoting toward sustainable, experience-driven retail formats.
Competitive Benchmarking and Market Concentration
The competitive landscape features a polarized structure between massive multinational chains like Frasers Group plc and agile independent bookstores such as Powell's Books Inc. Market concentration is moderate-to-high in sporting goods, while hobby and musical instrument segments remain fragmented, offering prime opportunities for strategic M&A activity.
Executive summary of the Sporting Goods, Hobby, Musical Instrument, and Book Stores Market market size
Our comprehensive research projects the Sporting Goods, Hobby, Musical Instrument, and Book Stores Market market size to expand dramatically from $567.11 Billion in 2026 to $941.48 Billion by 2033, achieving a robust 7.51% CAGR driven by experiential retail and e-commerce innovation.
Projected growth trajectory from 2027 to 2033
Based on our econometric models, the market is set to accelerate significantly through the forecast window. Generating a 7.51% CAGR, total market valuation will scale from its 2026 baseline of $567.11 Billion to reach $941.48 Billion by 2033, propelled by rising disposable incomes and specialty retail demand.
Segmentation analysis across product categories
The market breaks down by primary type into Sporting Goods Stores, Hobby, Toy, Game Stores, Musical Instrument And Supplies Stores, and Book Stores. Sub-segments like Independent Bookstores, Audio And Sound Equipment Stores, and Remote-Controlled Vehicles Stores each play distinct roles in capturing targeted consumer demographics.
Geographic distribution and regional performance dynamics
Regional performance varies based on local disposable income and cultural emphasis on leisure. North America leads consumption, supported by massive footprints from Barnes & Noble Inc. and Academy Sports + Outdoors, while Asia-Pacific registers the fastest growth due to expanding middle-class populations and urbanization.
In-depth regional review of key consumption hubs
North America dominates market share, sustained by robust distribution networks and high per-capita spending on outdoor and hobby goods. Meanwhile, European markets exhibit steady demand for specialized musical instruments and traditional literature, navigated expertly by regional powerhouses like Thomann GmbH.
Strategic positioning of leading companies
Industry leaders maintain distinct strategic moats. Dick's Sporting Goods Inc. leverages experiential big-box stores, whereas Hobby Lobby Stores Inc. dominates crafting materials through extensive private-label strategies. Digital-first innovators like Musician's Friend Inc. capture high-margin online instrument sales through aggressive digital marketing.
Porter's Five Forces analysis of the competitive environment
Supplier power remains moderate due to specialized manufacturing requirements for musical gear and sporting goods. Buyer power is high given intense price transparency from online e-book retailers. Threat of substitutes is mitigated by the tactile, sensory nature of physical books, instruments, and hobby crafting materials.
SWOT analysis of the industry ecosystem
Key strengths include strong consumer emotional connection to hobbies and sports. Weaknesses involve high inventory carrying costs. Opportunities emerge in immersive AR/VR in-store gaming experiences. Threats stem from macroeconomic inflation squeezing discretionary spending on non-essential collectibles and musical equipment.
Value chain analysis from raw materials to end-users
The value chain originates with raw material sourcing—such as timber for guitars and textiles for apparel—flowing through specialized manufacturing hubs, major global freight ports, and regional distribution centers before reaching exclusive showrooms, dealer stores, and e-commerce platforms operated by firms like Half Price Books Inc.
Investment insights and high-potential areas
Strategic investors should target omnichannel enablers and niche hobby platforms. Companies integrating immersive digital tools into physical stores—such as live music jam spaces or interactive board game cafes—demonstrate superior customer lifetime value and represent prime targets for private equity deployment.
Conclusion and key strategic takeaways
The Sporting Goods, Hobby, Musical Instrument, and Book Stores Market analysis confirms a lucrative, evolving landscape. Reaching $941.48 Billion by 2033, success hinges on blending physical experiential retail with seamless digital inventory management to satisfy modern, highly discerning enthusiast consumers.
Research methodology used for baseline estimations
Our baseline estimates are triangulated by cross-referencing trade registry data, primary executive interviews with leaders from firms like Cabela's Inc. and Michaels Stores Inc., and secondary macroeconomic indicators, ensuring rigorous, defensible market sizing across all sub-segments.
Scope of the report and coverage parameters
This report covers global revenue streams across sporting goods, toys, hobbies, musical instruments, and bookstores from 2026 to 2033. Excluded from this scope are second-hand automotive hobby parts and industrial sporting manufacturing, focusing purely on consumer-facing retail and wholesale establishments.
Recent developments, partnerships, and strategic corporate moves
Recent industry momentum is defined by major omnichannel acquisitions and supply chain diversification. Enterprises like Canadian Tire Corporation Limited and Tractor Supply Company have expanded their recreational footprints, forging strategic logistics partnerships to mitigate global freight disruptions and enhance direct-to-consumer delivery speeds.